CBAM 2026: What Changes for Indian Exporters Under the Definitive Regime
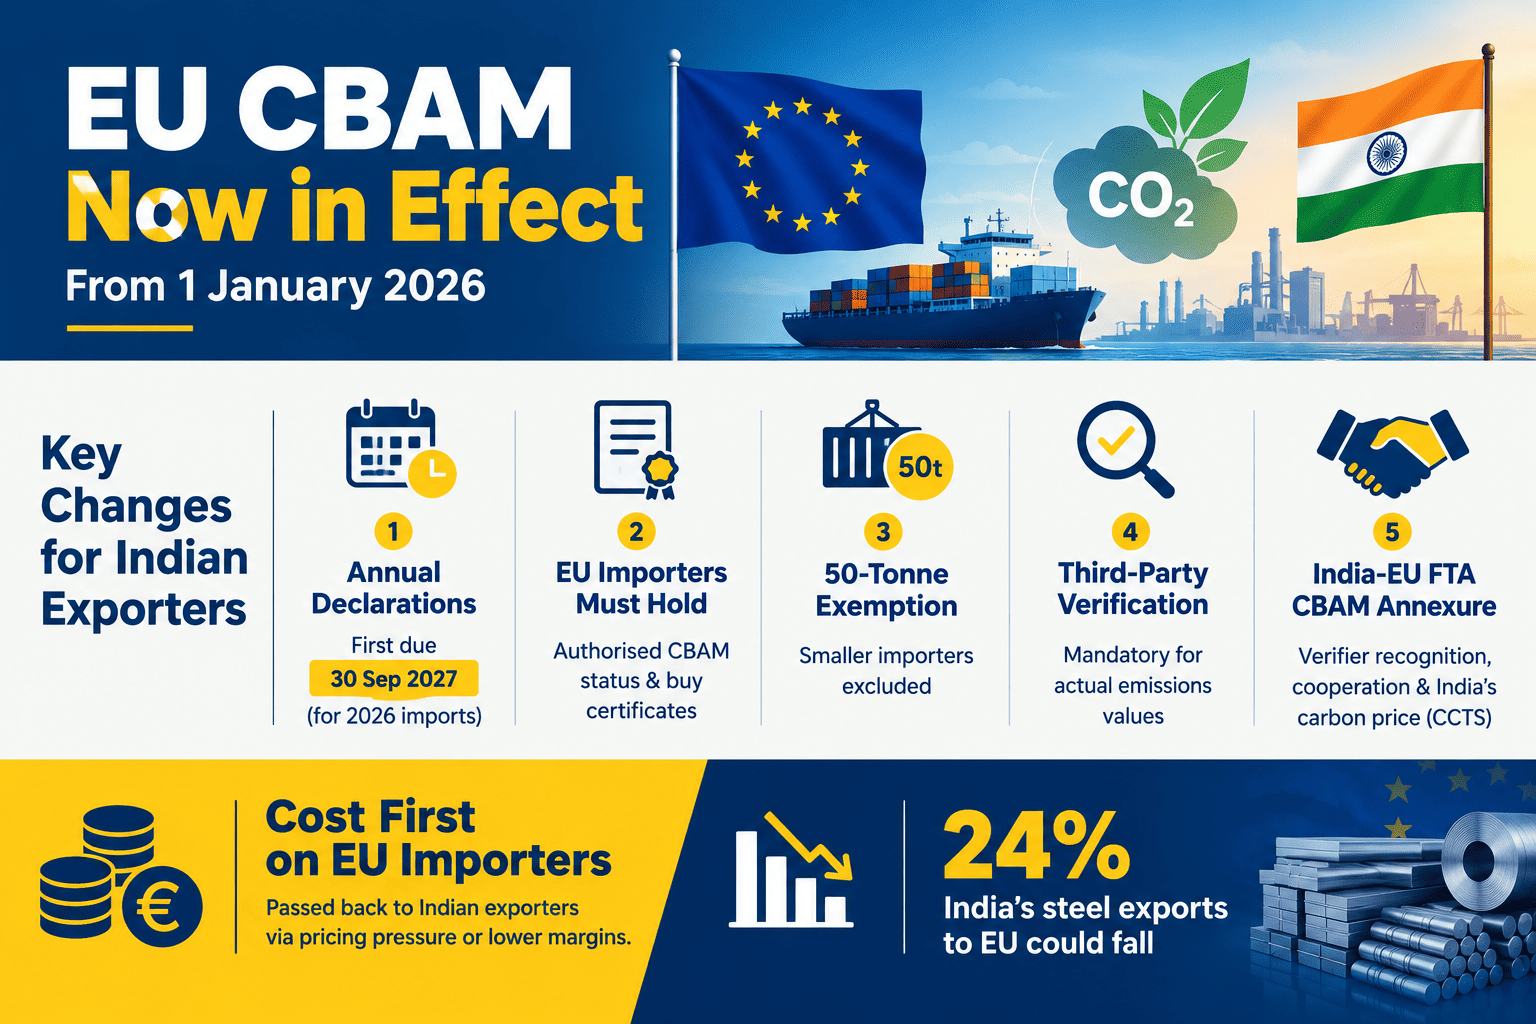
Direct Answer: The EU’s Carbon Border Adjustment Mechanism (CBAM) entered its definitive regime on 1 January 2026, ending the transitional reporting-only phase and introducing binding financial obligations for importers of carbon-intensive goods. For Indian exporters of steel, aluminium, cement, fertilisers, and hydrogen, the key changes are: (1) Annual declarations replace quarterly reporting, with the first declaration and certificate surrender due by 30 September 2027 for 2026 imports; (2) EU importers must now hold authorised CBAM declarant status before importing, and must purchase and surrender CBAM certificates corresponding to embedded emissions; (3) a 50-tonne de minimis exemption removes smaller importers from the regime; (4) third-party verification by EU-accredited bodies becomes mandatory for actual emissions values; and (5) the India-EU FTA concluded in January 2026 includes a dedicated CBAM annexure covering verifier recognition, technical cooperation, and a framework for recognising India’s domestic carbon price under the Carbon Credit Trading Scheme (CCTS). The financial burden falls first on EU importers, but the economic cost is expected to be passed back to Indian exporters through pricing pressure or reduced margins. ICRIER estimates India’s steel exports to the EU could fall by 24 per cent under CBAM.
📅 Published August 24, 2026🔄 Updated August 24, 2026⏱ 12 min read✍️ GTsetu Editorial Team
6
Sectors Covered by CBAM
50t
De Minimis Threshold
30 Sep 2027
First Declaration Deadline
24%
Projected Steel Export Drop to EU
January 2026 marked a fundamental shift in how carbon-intensive goods enter the European Union. The Carbon Border Adjustment Mechanism (CBAM) moved from its transitional phase, a reporting exercise with no financial consequence, into its definitive regime, where carbon emissions embedded in imported steel, aluminium, cement, fertiliser, hydrogen, and electricity carry a direct financial cost.
For Indian exporters, the change is structural, not incremental. What was previously a quarterly emissions disclosure obligation has become an annual declaration with certificate purchase and surrender requirements. EU importers, the parties legally liable under CBAM, must now be authorised declarants before they can import covered goods, and they must acquire CBAM certificates matching the embedded emissions of those imports:15]. The financial burden sits formally with the EU importer, but the economic incidence will be negotiated between buyer and seller, and Indian producers with higher carbon intensity face the greatest exposure.
This guide focuses exclusively on what the definitive regime changes for Indian exporters: the new legal obligations, the deadlines that matter, the mechanics of verification and certificate surrender, the India-EU FTA annexure on CBAM, and the domestic carbon market infrastructure India is building in response. For the partnership and verification infrastructure that supports compliant cross-border trade, see our guides on supply chain partners and why trust breaks in global deals.
💡 Who This Guide Is For
Indian exporters of steel, aluminium, cement, fertilisers, and hydrogen; EU importers sourcing from India; compliance and trade finance teams at Indian manufacturers; export promotion councils and industry bodies; and business development professionals building India-EU trade partnerships under the new carbon regime.
⚖️ Regulatory Disclaimer
This guide provides commercial and regulatory context on the CBAM definitive regime as it applies to Indian exporters. It is not legal, tax, or compliance advice. CBAM rules, implementing regulations, and India-EU FTA provisions continue to evolve. Always consult qualified EU and Indian legal counsel, accredited verifiers, and official EU and Indian government sources before making compliance decisions.
SECTION 1
1 What Actually Changed on 1 January 2026
🎯 The Core Shift
CBAM stopped being a reporting exercise and became a financial and legal compliance regime. Under the transitional period (October 2023 – December 2025), importers reported embedded emissions quarterly, but faced no payment obligation and no authorisation requirement. From 1 January 2026, the definitive regime introduced three structural changes simultaneously: mandatory authorisation for importers, annual declaration with certificate surrender, and third-party verification for actual emissions values.
📋
Authorisation Required
EU importers must hold authorised CBAM declarant status before importing covered goods. Applications had to be submitted via the CBAM Registry by 31 March 2026 at the latest.
📅
Annual, Not Quarterly
Reporting frequency changed from quarterly submissions to a single annual CBAM declaration. The first declaration covers 2026 imports and is due by 30 September 2027.
💰
Financial Obligation
Importers must purchase and surrender CBAM certificates matching the embedded emissions of imported goods. This is the first time CBAM carries a direct carbon cost.
✅
Verification Mandatory
Emissions reports based on actual values must be verified by an accredited third-party verifier. Default values remain available but may carry higher certificate costs.
📊
50-Tonne Exemption
A new mass-based de minimis threshold exempts importers whose annual cumulative imports of CBAM goods (excluding hydrogen and electricity) stay below 50 tonnes.
🔄
Quarterly Certificate Holding
From 2027, authorised declarants must hold a sufficient number of CBAM certificates on a quarterly basis, not just at the annual surrender date.
📌 The Practical Implication for Indian Exporters
Under the transitional regime, Indian exporters provided emissions data to EU importers on a voluntary cooperation basis with no direct financial consequence. Under the definitive regime, that data now determines a cash cost, the number of CBAM certificates the importer must purchase and surrender. Where verified actual emissions are unavailable, default values apply, and these are typically conservative (higher) estimates that increase the importer’s certificate obligation. The commercial pressure on Indian exporters to provide verified, plant-level emissions data is therefore direct and immediate.
SECTION 2
2 Transitional vs Definitive Regime: Key Differences
The shift from transitional to definitive is not a gradual tightening, it is a categorical change in what CBAM requires. The table below summarises the differences that matter most for Indian exporters and their EU buyers.
Dimension
Transitional Period (Oct 2023 – Dec 2025)
Definitive Regime (from 1 Jan 2026)
Reporting frequency
Quarterly CBAM reports
Annual CBAM declaration
Financial obligation
None, reporting only
Purchase and surrender CBAM certificates
Authorisation
Not required
Authorised CBAM declarant status mandatory
Emissions values
Mandatory use of actual values from Aug 2024
Choice of verified actual values or default values
Verification
Not required
Mandatory for actual values; accredited verifier required,
De minimis exemption
€150 per consignment
50 tonnes cumulative annual mass,
Certificate holding
N/A
Quarterly from 2027; annual surrender by 30 Sep,
First compliance deadline
Quarterly reports throughout 2024–2025
30 September 2027 for 2026 imports,,
Annual
Declaration frequency replaces quarterly reporting
Certificates
The carbon cost instrument, purchased and surrendered
Verified
Actual emissions must be verified by accredited third party
50t
Cumulative annual threshold for exemption
SECTION 3
3 The New Authorisation Requirement
🔑 Who Needs Authorisation
From 1 January 2026, importers of CBAM goods must hold authorised CBAM declarant status to import covered goods into the EU customs territory. Authorisation is granted by the competent authority in the EU member state where the importer is established, following an application through the CBAM Registry,. Importers had to submit applications before their first import and by 31 March 2026 at the latest.
🏛️
Who Applies
The EU importer, the party submitting the customs declaration for release for free circulation in its own name and on its own account, is the authorised declarant. This is not the Indian exporter,.
📝
How to Apply
Applications are submitted through the CBAM Registry, the EU’s dedicated IT system for declarations, certificate management, and compliance monitoring,.
⚠️
Indirect Representatives
Indirect customs representatives are not covered by the 50-tonne de minimis exemption and must be authorised if they import CBAM goods on behalf of others.
🚫
Import Without Authorisation
Importers exempt under the 50-tonne threshold can import without authorisation, but must use the TARIC document code Y137 in the customs declaration.
✨ What This Means for Indian Exporters
While the authorisation obligation sits with the EU importer, Indian exporters should confirm that their EU buyers hold authorised declarant status, or qualify for the 50-tonne exemption, before finalising shipments. An importer without authorisation cannot legally import CBAM goods, creating delivery risk and potential contractual breach. This is a standard due diligence point for business partnership contracts and cross-border business partnerships.
SECTION 4
4 Annual Declaration and the September 2027 Deadline
📅 The Compliance Calendar
The definitive regime replaces quarterly reporting with a single annual CBAM declaration. The first declaration, covering all relevant goods imported during the 2026 calendar year, must be submitted by 30 September 2027. The same deadline applies to the surrender of the corresponding number of CBAM certificates,,.
The annual declaration must contain: the total quantity of each type of CBAM good imported in the previous year (in tonnes, or MWh for electricity); the total embedded emissions of those goods (in tonnes CO₂e per tonne or per MWh); the total number of CBAM certificates that must be surrendered, accounting for any carbon price already paid in the country of origin and the free allocation adjustment; and copies of verification reports from accredited verifiers where actual values are used.
1
2026 Imports Occur
EU importers import CBAM goods from India and other third countries throughout the 2026 calendar year. Indian exporters must provide embedded emissions data, preferably verified actual values, for each shipment.
2
Emissions Data Collection and Verification
Indian exporters compile plant-level emissions data. Where actual values are used, an accredited verifier must verify the embedded emissions report. India’s NABCB is working toward mutual recognition with EU accreditation bodies,.
3
Certificate Purchase
EU importers purchase CBAM certificates in the CBAM Registry to cover the embedded emissions of 2026 imports. Certificate prices are linked to EU ETS allowance prices,.
4
Declaration Submission
By 30 September 2027, the authorised CBAM declarant submits the annual declaration and surrenders the corresponding CBAM certificates,.
⚠️ Why 2027 Matters Now
The September 2027 deadline may seem distant, but the emissions data that supports it is being generated right now, from January 2026 imports onward. Indian exporters who wait until 2027 to build emissions monitoring systems will be assembling historic data retroactively, with limited ability to influence its quality or verifiability. The Commerce Department’s outreach to exporters is focused precisely on this gap,.
SECTION 5
5 CBAM Certificates: The Financial Obligation
💰 The Carbon Cost Instrument
CBAM certificates are the financial instrument through which the carbon cost of embedded emissions is paid. EU importers (or their indirect customs representatives) purchase certificates from national authorities at a price linked to the EU ETS allowance price, and surrender them against the embedded emissions reported in their annual CBAM declaration,. The number of certificates required is calculated from the embedded emissions, adjusted for any carbon price already paid in the country of production, and for the free allocation adjustment reflecting EU ETS free allowances to domestic producers.
📊
Certificate Price
Linked to EU ETS allowance prices. The actual cost per tonne of CO₂e fluctuates with the EU carbon market,.
🔄
Quarterly Holding (2027)
From 1 January 2027, authorised declarants must hold sufficient certificates on a quarterly basis during the import year, not just at the annual surrender date.
➖
Carbon Price Deduction
A carbon price already paid in the country of origin can be deducted, but only if it was effectively paid and adequately evidenced,.
📉
Free Allocation Adjustment
Reflects the free EU ETS allowances granted to domestic EU producers, reducing the certificate obligation proportionally.
✨ The Evidence Requirement Is the Binding Constraint
Under CBAM rules, a domestic carbon price is not automatically deducted. The cost must have been effectively paid and evidenced with an auditable, entity-level record. This is the specific gap that India’s Carbon Credit Trading Scheme (CCTS) must fill if Indian exporters are to claim deductions and reduce their effective CBAM cost,. For exporters building verified supply chain partnerships, this connects directly to supply chain partner frameworks and trust infrastructure in global deals.
SECTION 6
6 The 50-Tonne De Minimis Exemption
📏 Small Importer Relief
The definitive regime introduces a new mass-based de minimis exemption. Importers whose cumulative net mass of CBAM goods (cement, iron and steel, fertilisers, and aluminium) does not exceed 50 tonnes in a calendar year are exempt from CBAM obligations, no authorisation, no declaration, no certificate surrender. The exemption does not apply to hydrogen or electricity, where CBAM obligations apply from the first import.
📦
Calculated Per Importer
The threshold is calculated per importer, regardless of how many consignments or indirect customs representatives are involved. Exceedance is based on cumulative annual mass across all CBAM goods.
🚫
Not for Indirect Reps
The de minimis exemption does not apply to indirect customs representatives, who are not “importers” under the CBAM Regulation.
⚡
Hydrogen and Electricity Excluded
For hydrogen and electricity, CBAM obligations apply from the very first import, the 50-tonne threshold does not apply.
📋
Customs Code Y137
Importers exempt under the threshold use TARIC document code Y137 in the customs declaration when importing CBAM goods without authorisation.
SECTION 7
7 Verification and Accreditation Rules
✅ Third-Party Verification
Under the definitive regime, emissions reports based on actual values must be verified by an accredited third-party verifier. Verifiers must be accredited by EU National Accreditation Bodies in accordance with EU Regulation 2018/2067,. The verification covers the embedded emissions calculation, the monitoring methodology, and the operator’s emissions report.
🏛️
EU-Accredited Verifiers
Verifiers must be accredited by an EU National Accreditation Body. As of early 2026, there were no NABCB-accredited Indian agencies recognised under EU Regulation 2018/2067, though some Indian validation and verification bodies operate under accreditation from other bodies.
📋
Monitoring Plan
Operators must establish a Monitoring Plan covering production processes, system boundaries, and emissions monitoring. The European Commission published ten guidance documents in August 2026 to support implementation, including sector-specific guidance for iron and steel and aluminium,.
🔄
Default Values Alternative
Importers may choose default values instead of verified actual values, but these are typically conservative (higher) estimates, increasing the certificate obligation and therefore the effective carbon cost,.
🤝
Mutual Recognition Path
The India-EU FTA annexure establishes a framework for mutual recognition of accreditation bodies, which, if implemented, would allow Indian verifiers to be recognised for CBAM purposes,.
SECTION 8
8 What This Means for Indian Exporters
India’s exposure to CBAM is concentrated in metals. According to NITI Aayog’s Trade Watch Quarterly, annual metals exports stood at approximately $34.8 billion in 2025, with iron, steel, and aluminium accounting for roughly 78 per cent of that trade,. The EU accounts for approximately 22 per cent of India’s combined steel and aluminium exports. In the iron and steel sector specifically, India’s trade exposure to the EU stands at 39.3 per cent, nearly two-fifths of its steel exports are destined for the European market,.
The challenge is compounded by carbon intensity. Indian metals have notably higher carbon intensity than the global average, primarily because primary steel production relies heavily on coal-based Blast Furnace–Basic Oxygen Furnace routes and coal-fired Direct Reduced Iron processes, rather than cleaner gas-based or Electric Arc Furnace routes,. A June 2026 working paper by ICRIER estimates that India’s steel exports to the EU could fall by 24 per cent under CBAM, based on simulations using the ICRIER Samriddhi Model,.
$34.8B
Annual metals exports (2025), with iron, steel, and aluminium at ~78%
39.3%
India’s steel export exposure to the EU market
24%
Projected decline in steel exports to EU under CBAM (ICRIER)
📌 The Commercial Transmission Mechanism
While the EU importer is the legal CBAM obligor, the economic cost is expected to be transmitted back to Indian exporters through lower margins, higher prices, or reduced competitiveness,. Where Indian producers cannot provide verified actual emissions data, EU buyers face higher certificate costs, which weakens the competitiveness of Indian shipments against lower-carbon rivals. This is especially relevant in price-sensitive commodity chains, where even a small increase in effective landed cost can alter sourcing decisions,.
SECTION 9
9 The India-EU FTA CBAM Annexure
🤝 A Framework for Mitigation
India and the EU concluded negotiations for a Free Trade Agreement on 27 January 2026 at the India-EU Summit. The agreement includes a dedicated Annex on Carbon Border Measures, a formal framework for cooperation and flexibility on CBAM implementation,.
🛡️
No Less Favourable Treatment
If the EU grants any flexibility under CBAM to other trading partners, India receives no less favourable treatment. This is an obligation under the FTA, not a discretionary concession,.
🔬
Technical Exchanges
The annexure establishes a Technical Dialogue on implementation, product scope, embedded emissions coverage, monitoring, reporting, and verification processes.
✅
Verifier Recognition
A framework for exploring mutual recognition of accreditation bodies for verifiers, which would allow Indian verifiers to be recognised for CBAM purposes,.
💰
Carbon Price Recognition
A framework for India to engage with the EU on recognising carbon prices paid domestically under India’s CCTS, potentially reducing the effective CBAM cost for Indian exporters.
✨ What the Annexure Delivers, and What It Doesn’t
The annexure does not suspend CBAM obligations. It creates a medium-term pathway to reduce compliance costs through verifier recognition and carbon price deduction, but only if the implementing details survive ratification and India’s domestic carbon market becomes operational and auditable. For exporters, the near-term action is unchanged: CBAM obligations under the definitive regime are live, and verified emissions data is the essential foundation for any future deduction or flexibility.
SECTION 10
10 India’s Domestic Carbon Market Response
India’s strategic response to CBAM is to build a domestic carbon pricing system that can generate the auditable, entity-level carbon cost records required for deductions under CBAM. The Carbon Credit Trading Scheme (CCTS) went live earlier this year, with trading regulations notified by the Central Electricity Regulatory Commission. A joint report by the Confederation of Indian Industry (CII) and IIM Ahmedabad, released in August 2026, sets out what India’s carbon market needs to deliver for exporters,.
📋
Auditable Registry
A well-designed domestic registry producing entity-level records of carbon costs paid, so exporters can claim valid deductions under CBAM,.
🔬
Robust MRV
Monitoring, Reporting, and Verification systems with independent verification of facility-level emissions, ensuring every Carbon Credit Certificate represents a genuine reduction,.
📊
Intensity-Based Targets
Emissions-intensity targets rather than absolute caps, allowing production growth while penalising weak emissions performance and rewarding carbon efficiency,.
💰
Price Certainty
A transparent price-collar methodology to give companies certainty for long-term investment decisions, with an illustrative reference range examined.
📌 The Strategic Logic
The CII-IIMA report frames the choice starkly: without a credible domestic carbon-pricing framework, Indian exporters of steel, cement, aluminium, fertilisers, and refined products will struggle to remain competitive under CBAM. The direction of travel across major trading partners, including Turkey, which gazetted its own emissions trading system, is consistent: the EU’s border mechanism is pushing large trading partners to build domestic carbon pricing that meets European evidentiary standards. The alternative is paying the carbon price to Brussels rather than into India’s own treasury,.
SECTION 11
11 Exporter Compliance Checklist
For Indian exporters of CBAM-covered goods, the definitive regime creates a set of practical obligations. The following checklist summarises the key actions, drawn from official EU guidance and Indian government outreach,,.
1
Confirm Your EU Buyer’s CBAM Status
Verify that your EU importer holds authorised CBAM declarant status, or qualifies for the 50-tonne de minimis exemption. An importer without authorisation cannot legally import CBAM goods, creating delivery and contractual risk.
2
Establish Plant-Level Emissions Monitoring
Set up a Monitoring Plan covering production processes, system boundaries, and emissions monitoring in line with CBAM methodology. The European Commission published ten guidance documents in August 2026, including sector-specific guides for iron and steel and aluminium,.
3
Engage an Accredited Verifier
Identify a verifier accredited by an EU National Accreditation Body. India’s NABCB is working toward mutual recognition under the India-EU FTA annexure, but as of early 2026 no Indian agency was recognised under EU Regulation 2018/2067,.
4
Collect Supply Chain Emissions Data
Precursors and upstream inputs contribute to embedded emissions. Work with your suppliers and logistics partners to collect traceable, verifiable emissions data across the value chain.
5
Monitor India’s CCTS Development
India’s Carbon Credit Trading Scheme, once operational and recognised by the EU, could provide the auditable carbon price record needed for CBAM deductions. Monitor policy developments and engage with the Commerce Department’s outreach programmes,.
6
Build Verified Supply Chain Partnerships
CBAM compliance depends on emissions data that flows across the supply chain. Verified, trusted partnerships, built through platforms like GTsetu, provide the foundation for traceable, auditable carbon data exchange. See supply chain partner frameworks and cross-border manufacturing partnerships.
SECTION 12
12 Building Verified Supply Chain Partnerships
CBAM compliance is not a solo exercise. The embedded emissions of any exported good include the emissions from its precursors, the raw materials, intermediate products, and inputs that go into its production. Indian steel exporters need emissions data from iron ore suppliers, coal suppliers, and logistics providers. Aluminium exporters need data from alumina refiners and power suppliers. The compliance chain extends across the entire value chain,.
This makes verified supply chain partnerships a practical CBAM readiness requirement, not a strategic aspiration. Exchanging commercially sensitive emissions data, production process details, energy consumption, raw material sourcing, requires confidentiality infrastructure, trusted counterparties, and auditable records. For related frameworks, see our guides on why trust breaks in global deals and business partnership contracts.
✨ The Verification Advantage
CBAM-ready supply chains require verified partner identities as their foundation. A manufacturer providing emissions data must be confirmed as the legal entity it claims to be, operating under the registration it presents. GTsetu’s 6-point government tie-up verification, legal name, registered address, registration number, company status, company type, incorporation date, provides this foundational layer, enabling secure, auditable data exchange across the supply chain. See supply chain partner guidance and partnership evaluation criteria.
SECTION 13
13 How GTsetu Supports CBAM-Ready Partnerships
🌐 Platform Spotlight, GTsetu
Verified Supply Chain Infrastructure for Carbon-Compliant Trade
CBAM compliance depends on data that flows across the supply chain, emissions data, production process details, raw material sourcing information. That data can only be exchanged with confidence between verified partners, using secure channels, under confidentiality frameworks. GTsetu provides the infrastructure that makes this possible: a government-tie-up verified B2B discovery environment where manufacturers, distributors, and suppliers connect with verified counterparts across 100+ countries, with built-in NDA workflows, encrypted document exchange, and zero broker commission. For Indian exporters building CBAM-ready supply chains, this is the foundational layer of trust that compliance requires. See our guides on supply chain partners and why trust breaks in global deals.
✅
Government Tie-Up Verification
6-point verification: legal name, registered address, registration number, company status, company type, incorporation date.
📄
Built-In NDA Workflow
Formalise confidentiality before sharing emissions data, production process details, or commercially sensitive supply chain information.
🔐
Encrypted Document Exchange
Secure channels for exchanging verified emissions reports, supplier data, and compliance documentation with audit trail.
🌍
100+ Countries
Verified network of manufacturers, distributors, and suppliers for building CBAM-ready supply chains across India, the EU, and global markets.
🚫
Zero Commission
No broker fees on any partnership, ensuring all commercial value stays between you and your verified partner.
Verified partner identity (6-point government tie-up)
✓ Mandatory for all companies
✗ Self-reported only
Secure emissions data exchange
✓ Encrypted workspace with audit trail
✗ Email risk, no audit trail
NDA before sensitive disclosure
✓ Built-in workflow
~ External legal needed
Supply chain partner evaluation framework
✓ Structured criteria and tools
✗ Ad hoc assessment
Zero broker commission
✓ Always
✗ Often 5–15%
100+ country coverage for supply chain diversification
✓ Yes
~ Geography-limited
FAQ
? Frequently Asked Questions
QWhen did the CBAM definitive regime start?
The CBAM definitive regime started on 1 January 2026. It replaced the transitional period (October 2023 to December 2025), which required quarterly emissions reporting only,. Under the definitive regime, importers must now hold authorised CBAM declarant status, submit annual CBAM declarations, and purchase and surrender CBAM certificates corresponding to the embedded emissions of imported goods,.
QWhat is the deadline for the first CBAM declaration?
The first annual CBAM declaration and the surrender of corresponding CBAM certificates is due by 30 September 2027, covering imports made during the 2026 calendar year,. This is the first time financial obligations, not just reporting, apply under CBAM. From 1 January 2027, authorised declarants must also hold a sufficient number of CBAM certificates on a quarterly basis.
QWhat is the 50-tonne de minimis exemption under CBAM?
The 50-tonne de minimis exemption applies to importers whose cumulative net mass of imported CBAM goods in the cement, iron and steel, fertilisers, and aluminium sectors does not exceed 50 tonnes in a given calendar year. If you are below this threshold, you are exempt from CBAM obligations, no authorisation, no declaration, no certificate surrender. However, the exemption does not apply to hydrogen or electricity, and it does not apply to indirect customs representatives.
QWhich sectors are covered by CBAM in 2026?
CBAM currently covers six sectors: iron and steel, aluminium, cement, fertilisers, electricity, and hydrogen,. These are the carbon-intensive goods for which embedded emissions must be reported and for which CBAM certificates must be surrendered. The EU has signalled that the scope may expand to additional sectors in future.
QWhat is an authorised CBAM declarant?
An authorised CBAM declarant is an importer who has been granted authorisation by the competent authority in an EU member state to import CBAM goods. Since 1 January 2026, importers must hold this status to import CBAM goods into the EU customs territory, unless they qualify for the 50-tonne de minimis exemption. Applications had to be submitted through the CBAM Registry before the first import and by 31 March 2026 at the latest.
QHow does the India-EU FTA affect CBAM for Indian exporters?
The India-EU FTA concluded in January 2026 includes a dedicated CBAM annexure. It covers: future flexibility (if the EU grants flexibility under CBAM to any trading partner, India receives no less favourable treatment); technical exchanges on implementation, product scope, and monitoring/reporting/verification; mutual recognition of accreditation bodies for verifiers; and a framework for India to engage with the EU on recognising carbon prices paid domestically under India’s Carbon Credit Trading Scheme (CCTS). This could reduce the effective CBAM cost for Indian exporters once India’s domestic carbon market is operational and auditable.
QWhat are the key changes from the transitional period to the definitive regime?
The major changes are: (1) Reporting frequency changed from quarterly to annual; (2) Financial obligations were introduced, importers must now purchase and surrender CBAM certificates; (3) Authorisation became mandatory; (4) A 50-tonne de minimis exemption was introduced; (5) Verification by accredited third-party verifiers became mandatory for actual emissions values; and (6) Quarterly certificate holding obligations start in 2027.
QHow can Indian exporters prepare for CBAM compliance?
Indian exporters should: (1) Confirm their EU buyer’s CBAM status (authorised declarant or de minimis exempt); (2) Implement robust emissions monitoring, reporting, and verification (MRV) systems at plant level; (3) Engage with accredited verifiers; (4) Ensure supply chain emissions data is traceable and verifiable; (5) Monitor the development of India’s Carbon Credit Trading Scheme (CCTS), which could provide deductions against CBAM costs; (6) Engage with the Commerce Department’s outreach programmes; and (7) Build verified supply chain partnerships to support carbon data exchange.
QWhat is the economic impact of CBAM on Indian steel exports?
A June 2026 working paper by ICRIER estimates that India’s steel exports to the EU could fall by 24 per cent under CBAM, based on simulations using the ICRIER Samriddhi Model. India’s trade exposure to the EU in iron and steel stands at 39.3 per cent of its steel exports. The impact is compounded by the carbon intensity of Indian metals production, which relies heavily on coal-based Blast Furnace–Basic Oxygen Furnace routes and coal-fired Direct Reduced Iron processes.
Building CBAM-Ready Supply Chain Partnerships?
Join 500+ verified manufacturers, suppliers, and distributors already building cross-border supply chain partnerships on GTsetu, with government-tie-up verification of six core credentials, built-in NDA workflows, encrypted document exchange, and zero broker fees across 100+ countries.
They represents the product, and research team behind GTsetu, a global B2B collaboration platform built to help companies explore cross-border partnerships with clarity and trust. The team focuses on simplifying early-stage international business discovery by combining structured company profiles, verification-led access, and controlled collaboration workflows.
With a strong emphasis on trust, and disciplined engagement, Team GTsetu shares insights on global trade, partnerships, and cross-border collaboration, helping businesses make informed decisions before entering deeper commercial discussions.