CBAM Explained: What Indian Exporters Need to Know About the EU Carbon Border Adjustment Mechanism
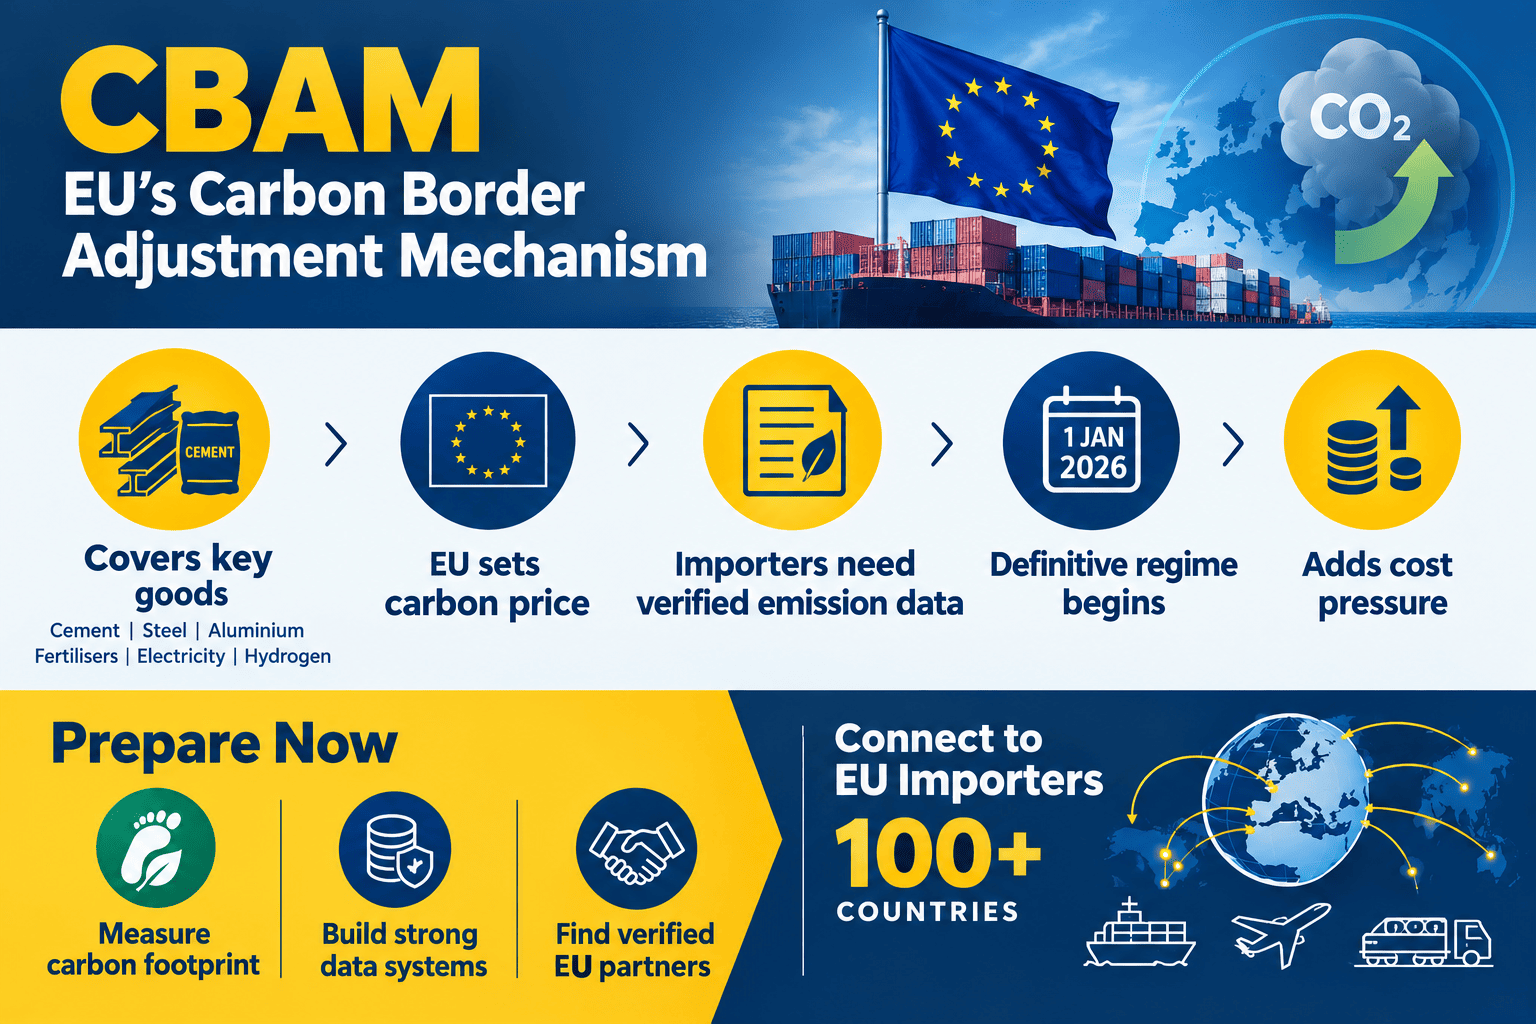
Direct Answer:CBAM (Carbon Border Adjustment Mechanism) is the European Union’s landmark climate policy that puts a carbon price on imports of carbon-intensive goods, cement, iron and steel, aluminium, fertilisers, electricity, and hydrogen, to prevent “carbon leakage” and ensure that imported goods face the same carbon costs as EU-produced goods under the EU Emissions Trading System (ETS). For Indian exporters, CBAM is a critical compliance and competitiveness issue. If you export any of these goods to the EU, your EU customers will require detailed, verified data on the embedded emissions of your products. From 1 January 2026, the definitive regime begins, meaning EU importers must purchase and surrender CBAM certificates, creating a direct cost pressure that will be passed down the supply chain. Preparing now, by measuring your carbon footprint, establishing robust data systems, and finding verified EU partners, is essential. GTsetu helps Indian exporters connect with government‑tie‑up verified EU importers and partners across 100+ countries, enabling secure data exchange and trusted cross-border collaboration.
📅 Published October 2, 2026🔄 Updated October 2, 2026⏱ 17 min read✍️ GTsetu Editorial Team
6
Covered Sectors
2026
Definitive Regime Begins
100+
Countries on GTsetu
0%
Broker Commission
The European Union’s Carbon Border Adjustment Mechanism (CBAM) represents one of the most significant changes to global trade rules in decades. For Indian exporters in carbon-intensive sectors, steel, aluminium, cement, fertilisers, and hydrogen, CBAM is not a distant policy debate; it is a direct commercial challenge that requires immediate action.
This guide explains CBAM in clear, practical terms for Indian exporters: what it is, why it exists, which sectors and goods are covered, how the mechanism works, what it means for your competitiveness, and, critically, how to prepare your business, measure your emissions, and find verified EU partners to maintain and grow your European market access. For related context, see our guides on global market research for manufacturers, manufacturing certifications for international trade, and cross-border manufacturing partnerships.
💡 Who This Guide Is For
Indian manufacturers, exporters, and trade professionals in CBAM-covered sectors (iron and steel, aluminium, cement, fertilisers, hydrogen, electricity) who export or plan to export to the EU. It is also relevant for EU importers sourcing from India, and for business development teams evaluating the commercial impact of CBAM on their supply chains.
⚖️ Legal & Compliance Disclaimer
This guide provides general commercial and compliance education on CBAM. It does not constitute legal, tax, or regulatory advice. CBAM rules are complex and evolving. Always consult qualified legal and compliance professionals and refer to official EU sources (EU Commission, DG TAXUD) for the most current regulations.
SECTION 1
1 What is CBAM?
🎯 Definition
CBAM (Carbon Border Adjustment Mechanism) is a European Union regulation that places a carbon price on imports of certain carbon-intensive goods. It is designed to prevent carbon leakage, the situation where EU companies relocate production to countries with less stringent climate policies to avoid carbon costs, by ensuring that imported goods face a carbon charge equivalent to what EU producers pay under the EU Emissions Trading System (ETS). CBAM is not a tariff or a trade barrier; it is an environmental policy tool that extends the EU’s carbon pricing to imports.
In practical terms, CBAM means that if you export steel, aluminium, cement, fertilisers, hydrogen, or electricity to the EU, your EU customer (the importer) will be required to report the embedded emissions of those goods and, from 2026, purchase CBAM certificates corresponding to those emissions. The cost of these certificates will be passed down the supply chain, directly affecting the price competitiveness of your products in the EU market.
CBAM is part of the EU’s Fit for 55 package, a set of legislative proposals to reduce EU greenhouse gas emissions by at least 55% by 2030 compared to 1990 levels. It is also aligned with the EU’s broader climate strategy and its commitment under the Paris Agreement.
Key Features of CBAM
🌍
Carbon Price on Imports
Puts a price on the carbon emissions embedded in imported goods, equivalent to the carbon price EU producers pay under the EU ETS.
📊
Embedded Emissions Reporting
Requires EU importers to report the direct and indirect emissions embedded in imported goods, based on verified data from the exporter.
📜
CBAM Certificates
From 2026, importers must purchase and surrender CBAM certificates corresponding to the emissions of their imports, creating a direct cost.
⚖️
Preventing Carbon Leakage
Ensures that EU climate ambition is not undermined by production shifting to countries with weaker climate policies.
🔄
Phased Implementation
Starts with a transitional reporting period (2023–2025) before the definitive regime begins on 1 January 2026.
🎯
Covered Sectors
Initially covers cement, iron and steel, aluminium, fertilisers, electricity, and hydrogen, sectors at high risk of carbon leakage.
SECTION 2
2 Why CBAM Exists: Carbon Leakage & Climate Goals
To understand CBAM, you must understand the problem it is designed to solve: carbon leakage. The EU has some of the world’s most ambitious climate policies, including a carbon price under its Emissions Trading System (ETS). This carbon price makes production more expensive for EU manufacturers. Without a border mechanism, EU companies could simply move production to countries with no carbon price, import the goods back into the EU, and avoid the carbon cost, while global emissions remain unchanged or even increase. This is carbon leakage.
💡 The Carbon Leakage Problem
Carbon leakage occurs when companies relocate carbon-intensive production from a jurisdiction with strict climate policies (like the EU) to one with laxer policies, to avoid carbon costs. This undermines the climate policy’s effectiveness and can lead to job losses and lost investment in the strict-policy jurisdiction. CBAM is the EU’s solution: by putting a carbon price on imports, it levels the playing field between EU and non-EU producers.
CBAM is also designed to incentivise decarbonisation in non-EU countries. By putting a price on embedded carbon, it creates a financial incentive for exporters in countries like India to invest in cleaner production technologies, renewable energy, and energy efficiency. Over time, this can drive global emissions reductions and support the transition to a low-carbon economy.
55%
EU target for emissions reduction by 2030 (vs. 1990 levels) under the Fit for 55 package
6
Sectors initially covered by CBAM: cement, iron & steel, aluminium, fertilisers, hydrogen, electricity
2026
Start of the definitive regime, when importers must purchase and surrender CBAM certificates
Global
CBAM is expected to influence other regions to adopt similar carbon border measures
✨ GTsetu Insight
CBAM is not just an EU issue; it is a global trade issue. As other countries consider similar mechanisms, Indian exporters who invest in measuring and reducing their carbon footprint now will be better positioned to compete in all major markets. This is also an opportunity to differentiate your products as low-carbon and to build stronger, more transparent relationships with EU partners. See our guide on cross-border business partnerships for how to structure these relationships.
SECTION 3
3 Who is Affected: EU Importers & Indian Exporters
CBAM creates obligations for EU importers and, by extension, impacts Indian exporters in covered sectors. Understanding the division of responsibility is critical for compliance and commercial planning.
Stakeholder
Obligations Under CBAM
What This Means for You
EU Importer (Authorised CBAM Declarant)
Register as an authorised CBAM declarant; report embedded emissions of imported goods; purchase and surrender CBAM certificates; keep records for 4 years.
Your EU customer is legally responsible for compliance. They will require detailed, verified emissions data from you to meet their obligations.
Indian Exporter (You)
No direct legal obligation under CBAM, but you must provide your EU customer with accurate, verified emissions data. You may also need to support verification by an accredited verifier.
You are commercially affected: your EU customer will ask for emissions data; failure to provide it may result in lost sales or higher costs. You may also face pressure to reduce your carbon footprint.
Non-EU Producers (Other Countries)
Same as Indian exporters: must provide emissions data to EU importers to maintain market access.
Competitors in other countries face the same pressure. Early movers in emissions measurement and reduction may gain a competitive advantage.
📌 The Data Demand
The most immediate impact for Indian exporters is the data demand. Your EU customer cannot comply with CBAM without your emissions data. If you cannot provide it, they may be forced to use default values (which are often higher and more costly) or may switch to a supplier who can. This makes emissions data a commercial necessity, not just a regulatory one. For more on data sharing, see our guide on why trust breaks in global deals.
SECTION 4
4 CBAM-Covered Sectors & Goods
CBAM initially covers six sectors. Not all goods within these sectors are covered, the regulation specifies particular CN (Combined Nomenclature) codes. If your product falls under one of these codes, you are in scope.
Sector
Covered Goods (Examples)
Key Emissions to Measure
Cement
Portland cement, aluminous cement, cement clinkers, etc.
Direct emissions from clinker production; indirect emissions from electricity use.
Direct emissions from electrolysis; indirect emissions from electricity (especially important for aluminium smelting).
Fertilisers
Nitric acid, ammonia, nitrogenous fertilisers, etc.
Direct emissions from ammonia and nitric acid production; indirect emissions from electricity.
Electricity
Electricity imported into the EU
Direct emissions from electricity generation; indirect emissions from the fuel supply chain.
Hydrogen
Hydrogen, including renewable and low-carbon hydrogen
Direct emissions from hydrogen production; indirect emissions from electricity and feedstock.
✨ Practical Takeaway
If you are unsure whether your product is covered, check the CBAM regulation’s Annex I, which lists the specific CN codes. You can also consult with your EU customer, they have a legal obligation to know and will have detailed guidance. For manufacturing certification and compliance more broadly, see our guide on manufacturing certifications for international trade.
SECTION 5
5 How CBAM Works: Reporting, Certificates & Costs
CBAM operates through a system of reporting, verification, and certificate surrender. Here is how it works in practice.
1
Exporter Measures Embedded Emissions
You (the Indian exporter) must measure the direct and indirect emissions embedded in your production process for the covered goods. This includes emissions from fuel combustion, chemical reactions, and electricity consumption. You need a robust system to collect this data and, ideally, have it verified by an accredited verifier.
2
Exporter Reports Data to EU Importer
You provide the emissions data to your EU customer (the importer), along with supporting documentation. The EU importer uses this data to prepare their CBAM declaration. The data must be accurate and verifiable, as the importer bears the legal risk if it is not.
3
EU Importer Reports to CBAM Authority
The EU importer submits an annual CBAM declaration to the competent national authority, reporting the embedded emissions of the imported goods. During the transitional period (2023–2025), this is a reporting-only obligation with no financial payment.
From 1 January 2026, the definitive regime begins. EU importers must purchase CBAM certificates from their national authority. The price of certificates is linked to the average weekly price of EU ETS allowances. The importer must surrender certificates corresponding to the embedded emissions of their imports.
5
Cost Passed Down the Supply Chain
The cost of purchasing CBAM certificates is a new cost for the EU importer. In most commercial relationships, this cost will be passed down to the exporter through price negotiations. The more carbon-intensive your production, the higher the CBAM cost, and the more pressure on your price competitiveness.
6
Reduction Incentive
The ultimate goal of CBAM is to incentivise decarbonisation. By putting a price on embedded carbon, it makes investments in cleaner production, renewable energy, and energy efficiency more financially attractive. Exporters who reduce their emissions will reduce their CBAM costs and maintain a competitive edge.
📌 CBAM Certificates vs. EU ETS Allowances
CBAM certificates are distinct from EU ETS allowances, but their price is linked. The price of a CBAM certificate is based on the average auction price of EU ETS allowances. This ensures that the carbon cost for imports is equivalent to the carbon cost for EU producers. For more on carbon pricing, see our guide on company global expansion and the regulatory landscape.
SECTION 6
6 CBAM Timeline: Transitional to Definitive Regime
CBAM is being implemented in phases. Understanding the timeline is essential for planning your compliance and commercial strategy.
Period
Phase
Key Obligations
Financial Impact
1 Oct 2023 – 31 Dec 2025
Transitional Period
EU importers must report embedded emissions of imported goods on a quarterly basis. No financial payments required.
No direct carbon cost, but reporting burden and data collection requirements for exporters.
1 Jan 2026 – 31 Dec 2034
Definitive Regime (Phased)
EU importers must purchase and surrender CBAM certificates. Free allocation under EU ETS is phased out, and CBAM is phased in.
Direct carbon cost begins. Cost increases annually as free allocation is reduced and CBAM is fully phased in by 2034.
From 2035
Full CBAM
CBAM is fully operational. No free allocation under EU ETS for covered sectors.
Full carbon cost on imports. Exporters must be highly carbon-efficient to remain competitive.
✨ GTsetu Insight
The transitional period (2023–2025) was a “learning period” for both EU importers and non-EU exporters. If you have not yet started preparing, you are already behind. The data you collect now will form the basis for your CBAM compliance and commercial negotiations from 2026 onwards. See our guide on how to source manufacturing materials internationally for broader supply chain resilience.
SECTION 7
7 Impact on Indian Exporters: Sectors, Costs & Competitiveness
India is one of the EU’s largest trading partners, and Indian exports of CBAM-covered goods, particularly steel and aluminium, are significant. CBAM will have a material impact on Indian exporters in these sectors.
Steel
India is a major steel exporter to the EU. CBAM will increase costs for Indian steel producers, especially those with higher carbon intensity.
Aluminium
Indian aluminium exports to the EU face significant CBAM exposure due to the energy-intensive nature of aluminium smelting.
Fertilisers
Indian fertiliser exports, particularly ammonia and nitric acid, will face CBAM costs based on embedded emissions.
Cement
While India’s cement exports to the EU are smaller, CBAM still applies to any covered cement products.
How CBAM Affects Indian Exporters
💰
Increased Costs
Your EU customer will face CBAM certificate costs. They will seek to pass these costs to you through lower prices or require you to share the burden. This directly impacts your margins.
📊
Data Requirements
You must measure and report embedded emissions. This requires investment in data collection systems, monitoring equipment, and potentially third-party verification.
🏆
Competitiveness Shift
Exporters with lower carbon intensity will have a competitive advantage. Those with high-carbon production may become uncompetitive in the EU market.
🔄
Supply Chain Pressure
EU importers may reconsider their sourcing strategies, potentially shifting to suppliers in countries with lower carbon intensity or to domestic EU production.
⚙️
Decarbonisation Imperative
CBAM creates a strong financial incentive to invest in cleaner production technologies, renewable energy, and energy efficiency.
🤝
Partnership Requirements
You will need to work closely with your EU customers to share data, agree on verification, and potentially renegotiate contracts. Trusted partnerships are essential. See our guide on cross-border manufacturing partnerships.
📌 The Opportunity in CBAM
While CBAM presents challenges, it also creates opportunities. Indian exporters who invest early in measuring and reducing their carbon footprint can differentiate themselves as low-carbon suppliers, potentially command premium prices, and build stronger, more resilient relationships with EU partners. See our guide on company global expansion for strategic considerations.
SECTION 8
8 How Indian Exporters Can Prepare for CBAM
Preparing for CBAM is not just about compliance; it is about protecting and enhancing your competitiveness in the EU market. Here is a step-by-step approach.
1
Map Your Products Against CBAM
Determine whether your products fall under CBAM-covered sectors and specific CN codes. If you are unsure, consult the official CBAM regulation or seek advice from trade associations or legal counsel. This is the first step to understanding your exposure.
2
Measure Your Embedded Emissions
Establish a system to measure direct and indirect emissions from your production processes. This may require installing monitoring equipment, using emission factors, and engaging with technical experts. Accurate data is the foundation of CBAM compliance.
3
Establish Robust Data Collection & Reporting
Implement systems to collect, manage, and report emissions data on an ongoing basis. This data will be required by your EU customers and may need to be verified by an accredited verifier. Consider digital tools and platforms to streamline this process.
4
Engage with Your EU Customers
Talk to your EU customers early. Understand their data requirements, timelines, and expectations. They are your partners in compliance and can provide valuable guidance on CBAM implementation. Clear communication is key to maintaining trust and market access.
5
Explore Decarbonisation Options
Identify opportunities to reduce your carbon footprint: energy efficiency improvements, renewable energy adoption, process optimization, and cleaner technologies. Reducing emissions reduces CBAM costs and enhances your long-term competitiveness.
6
Find Verified EU Partners
Work with trusted, verified EU importers and partners who can support your CBAM compliance and help you navigate the regulatory landscape. Platforms like GTsetu can help you find and verify these partners securely. See our guide on supply chain partners for more.
7
Seek Expert Advice
CBAM is complex and evolving. Engage with legal, compliance, and technical experts who can guide you through the requirements and help you develop a robust compliance strategy. For partnership and contract guidance, see our guide on business partnership contracts.
✨ GTsetu Insight
Preparing for CBAM is a cross-functional effort involving operations, finance, legal, and commercial teams. It is also an opportunity to strengthen your relationships with EU partners by demonstrating transparency, reliability, and a commitment to sustainability. Use the partnership evaluation criteria to assess your EU partners and build a resilient, compliant supply chain.
SECTION 9
9 Finding Verified EU Importers & Partners
Your ability to comply with CBAM and maintain your EU market access depends on the strength of your relationships with EU importers and partners. These relationships must be built on trust, transparency, and verified credentials.
🎯 The Partner Challenge
Finding the right EU partners, those who are credible, committed to sustainability, and capable of supporting your CBAM compliance, is challenging. Traditional methods like trade fairs, directories, and cold outreach are slow, unverified, and risky. You need a secure, verified environment where you can discover, evaluate, and engage with trusted EU importers and partners.
🔍
Discover Verified Partners
Use a platform that verifies company credentials through government sources. GTsetu verifies legal name, registered address, registration number, company status, company type, and incorporation date. This is your foundation for trust.
🕵️
Explore Anonymously
Before revealing your identity, browse partner profiles and assess their fit. GTsetu’s anonymous discovery allows you to evaluate potential partners without exposing your company details until you are ready.
📄
Execute NDAs Securely
Before sharing sensitive emissions data, pricing, or product specifications, execute a mutual NDA. GTsetu’s built-in NDA workflow ensures confidentiality from the first interaction, with a digital audit trail.
🔐
Collaborate Securely
Share emissions data, reports, and commercial documents through encrypted channels. GTsetu’s secure workspace ensures your data is protected in transit and at rest, with access controls and audit trails.
🤝
Build Long-Term Partnerships
CBAM is not a one-time compliance exercise; it is an ongoing requirement. Build long-term partnerships with EU importers based on trust, transparency, and mutual commitment to sustainability.
💼
Zero Commission
GTsetu charges zero commission on any partnership formed. Your commercial terms remain between you and your partner. This makes GTsetu a cost-effective alternative to traditional brokers and agents. See our guide on international business development consulting for comparison.
✨ GTsetu Insight
Finding the right EU partner is not just about compliance; it is about building a resilient, competitive supply chain that can adapt to the changing regulatory landscape. GTsetu’s verified network and secure collaboration tools give you the infrastructure you need to succeed in the CBAM era. See our guide on B2B matchmaking tools for more on how to find partners efficiently.
SECTION 10
10 How GTsetu Helps Indian Exporters with CBAM
🌐 Platform Spotlight, GTsetu
Your Verified Gateway to EU Importers & Partners
CBAM is changing the rules of trade with the EU. To succeed, you need to find and partner with EU importers who are credible, committed to sustainability, and capable of supporting your CBAM compliance. GTsetu provides the verified, secure platform to make this happen. We connect Indian exporters with government‑tie‑up verified EU importers and partners across 100+ countries, with built-in NDA workflows and encrypted collaboration. Every company on GTsetu is verified using direct government tie‑ups across six essential credentials: legal name, registered address, registration number, company status, company type, and date of certificate of incorporation. GTsetu does not verify industry certifications, emissions data, or financial standing; those must be exchanged and validated directly between partners.
✅
Government Tie‑Up Verification
6‑point verification: legal name, registered address, registration number, company status, company type, incorporation date.
📜
Certifications & Compliance
GTsetu does not verify these. They must be exchanged directly between partners during due diligence.
🕵️
Anonymous Discovery
Explore verified EU importer and partner profiles without revealing your identity until mutual interest is confirmed.
📄
Built-In NDA Workflow
Formalise confidentiality before sharing any emissions data, product specifications, pricing, or proprietary information, with a full digital audit trail.
🚫
Zero Commission
No broker fees on any deal, whether a distribution agreement, supply contract, or technology partnership.
🔐
Encrypted Collaboration
All documents and communications encrypted in transit and at rest. Secure B2B collaboration from first contact.
🌍
100+ Countries
Active verified network for EU importers, distributors, and supply chain partners.
QWhat is CBAM (Carbon Border Adjustment Mechanism)?
CBAM is the EU’s Carbon Border Adjustment Mechanism, a policy tool that puts a carbon price on imports of certain carbon-intensive goods entering the EU. It aims to prevent “carbon leakage”, where EU companies move production to countries with less strict climate policies, by ensuring that imported goods face a carbon cost equivalent to what EU producers pay under the EU Emissions Trading System (ETS).
QWhich sectors are covered by CBAM?
CBAM initially covers six sectors: cement, iron and steel, aluminium, fertilisers, electricity, and hydrogen. These are considered high-risk for carbon leakage and account for a significant share of EU industrial emissions. Not all goods within these sectors are covered, the regulation specifies particular CN codes.
QWho needs to comply with CBAM?
CBAM compliance obligations fall on EU importers who bring covered goods into the EU. However, Indian exporters in these sectors are directly affected because they must provide their EU customers with verified emissions data and may face increased costs. Authorised CBAM declarants in the EU are responsible for reporting and surrendering CBAM certificates.
QWhat is the CBAM transitional period?
The CBAM transitional period runs from 1 October 2023 to 31 December 2025. During this phase, EU importers must report the embedded emissions of imported goods but do not pay a carbon price. From 1 January 2026, the definitive regime begins, and importers must purchase and surrender CBAM certificates corresponding to the emissions of their imports.
QHow can Indian exporters prepare for CBAM?
Indian exporters should: (1) Map their products against CBAM-covered sectors; (2) Measure and verify the embedded emissions of their production processes; (3) Establish robust data collection and reporting systems; (4) Engage with EU customers to understand their data requirements; (5) Explore decarbonisation options to reduce CBAM costs; and (6) Find verified EU importers and partners through platforms like GTsetu.
QDoes CBAM apply to all Indian exports to the EU?
No, CBAM only applies to specific goods within the six covered sectors: cement, iron and steel, aluminium, fertilisers, electricity, and hydrogen. Not all exports from these sectors are covered, the regulation specifies particular CN codes. Indian exporters whose products fall under these codes will be affected.
QHow does GTsetu help Indian exporters with CBAM?
GTsetu helps Indian exporters find and verify EU importers and partners across 100+ countries. With government-tie-up verification of six core credentials (legal name, registered address, registration number, company status, company type, incorporation date), built-in NDA workflows, and zero broker commission, GTsetu enables exporters to establish trusted partnerships, ensuring they can share sensitive emissions data securely and build compliant supply chains.
Ready to Find Verified EU Partners and Comply with CBAM?
Join 500+ verified manufacturers, exporters, and importers already building cross-border partnerships on GTsetu, with government‑tie‑up verification of six core credentials, built-in NDA workflows, and zero broker fees across 100+ countries. Start building your CBAM-ready supply chain today.
They represents the product, and research team behind GTsetu, a global B2B collaboration platform built to help companies explore cross-border partnerships with clarity and trust. The team focuses on simplifying early-stage international business discovery by combining structured company profiles, verification-led access, and controlled collaboration workflows.
With a strong emphasis on trust, and disciplined engagement, Team GTsetu shares insights on global trade, partnerships, and cross-border collaboration, helping businesses make informed decisions before entering deeper commercial discussions.