Why Vietnam Is Becoming an Important Manufacturing Partner for Global Companies
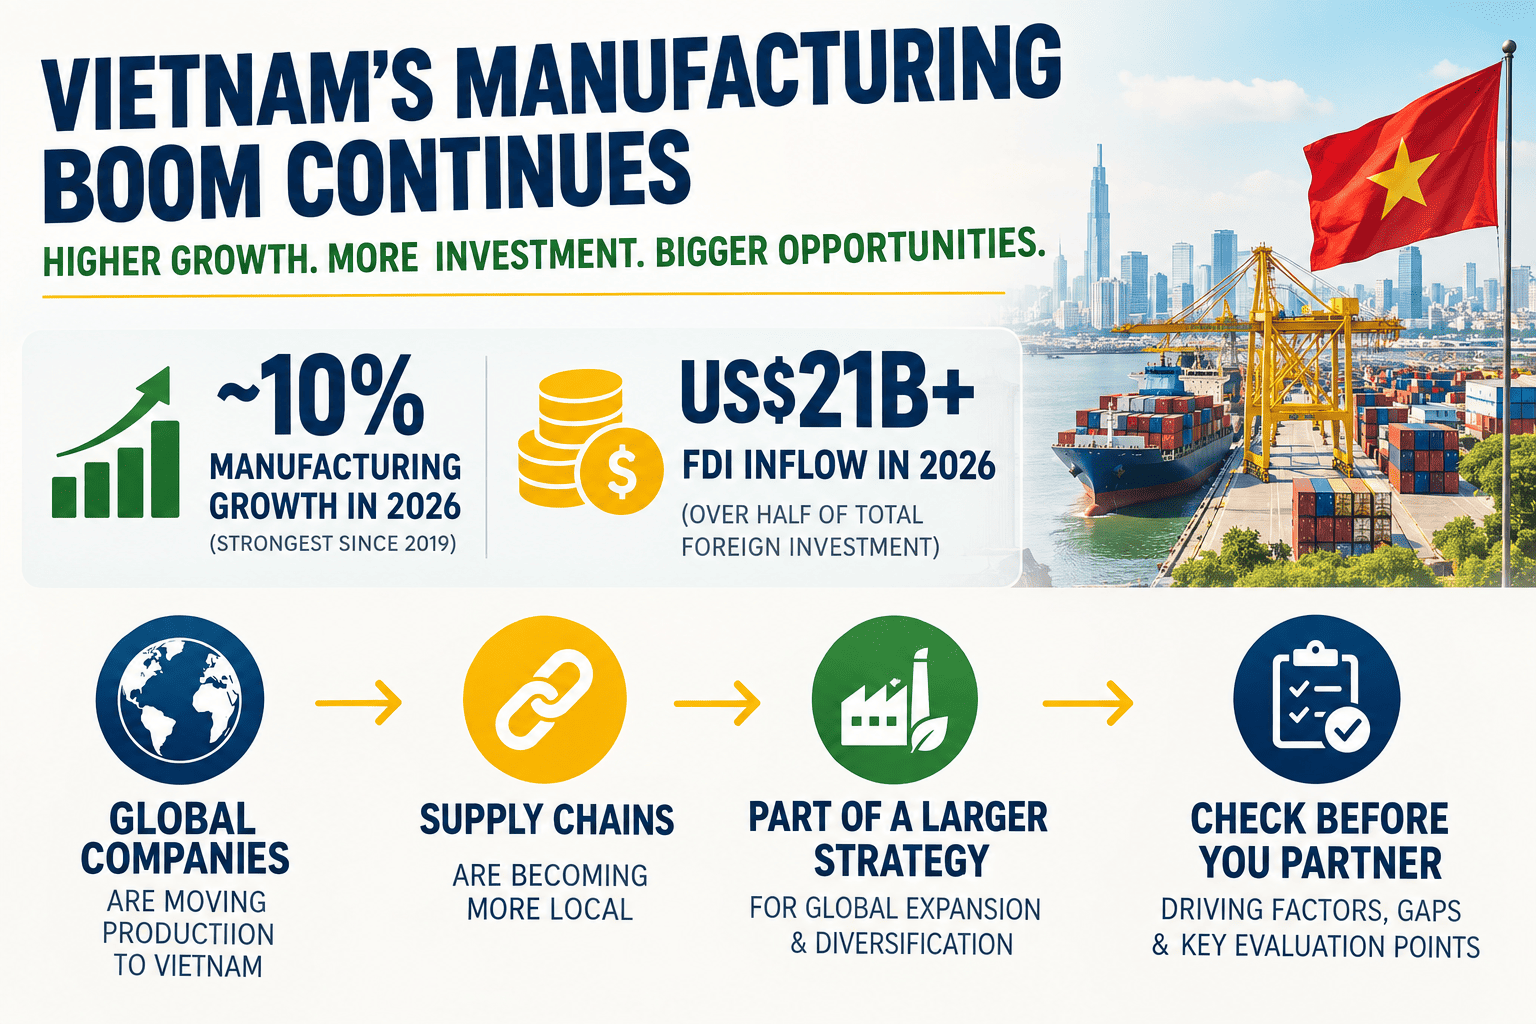
Vietnam’s manufacturing sector grew nearly 10 percent in 2026, its strongest performance since 2019, and pulled in over US$21 billion in FDI, more than half of the country’s total foreign investment for the year. That is not a one-off spike. It is the continuation of a decade-long shift in which global companies have moved production, and increasingly entire supplier relationships, into Vietnam as part of broader global expansion and supply chain diversification strategies. This article looks at what is actually driving that shift, where Vietnam still has real gaps, and what a company needs to check before treating a Vietnamese manufacturer as a long-term partner rather than a one-off supplier.
📅 Published June 18, 2026⏱ 12 min read✍️ GTsetu Editorial🔄 Updated September 5, 2026
A decade ago, Vietnam’s pitch to global manufacturers was straightforward: cheaper labour than China, reasonable infrastructure, and a government eager to court foreign capital. That pitch still holds some truth, but it is no longer the whole story. Vietnam has become a genuine node in global value chains, not just a lower-cost assembly line, and the companies moving production there today are increasingly looking for long-term manufacturing partnerships and cross-border manufacturing partnerships within global supply chains, not just a cheaper quote.
Section 1
Vietnam’s Manufacturing Rise in Numbers
The scale of Vietnam’s manufacturing expansion is easiest to see in its recent economic data. In 2026, manufacturing and processing was the single largest driver of Vietnam’s overall growth, and the sector’s contribution to GDP, exports, and state revenue all moved in the same direction: up.
9.97%
Growth in manufacturing and processing output in 2026, Vietnam’s strongest performance since 2019
US$21.01B
FDI into Vietnam’s manufacturing and processing sector in 2026, 54.7% of total FDI inflows
US$421.47B
Processed industrial exports in 2026, accounting for 88.7% of total merchandise exports
#3
Vietnam’s rank in the 2026 Asia Manufacturing Index among regional peers
Behind these headline figures is a more specific pattern worth noting: a large share of 2026’s FDI came not from brand-new entrants but from existing investors expanding capacity, upgrading technology, and extending operational timelines. That is a meaningfully different signal than first-time capital inflow. It suggests multinational manufacturers already operating in Vietnam are choosing to deepen their commitment rather than test the market and move on, a pattern more consistent with long-term partnership formation than opportunistic, one-off sourcing.
💡 Why this distinction matters
New-entrant FDI tells you a country is attractive on paper. Capital-adjustment FDI, existing investors putting more money in, tells you the experience of actually operating there has met or exceeded expectations. Vietnam’s 2026 numbers lean heavily toward the latter, which is a stronger signal for companies evaluating whether to commit to a Vietnamese manufacturing partner for the long term.
Section 2
Why Global Companies Are Choosing Vietnam
The Core Drivers
No single factor explains Vietnam’s rise. It is a combination of trade positioning, government policy, workforce economics, and geography that together make Vietnam a lower-risk, higher-upside choice than it was a decade ago.
1
One of the Most Trade-Integrated Economies in Asia
15+ free trade agreements, WTO and ASEAN membership
Trade AccessTariff Advantage
Vietnam has entered into more than 15 free trade agreements with partners across every continent, including the EU–Vietnam Free Trade Agreement and the Comprehensive and Progressive Agreement for Trans-Pacific Partnership, on top of its WTO and ASEAN membership. For manufacturers exporting from Vietnam, this translates directly into lower tariffs and faster customs clearance into major markets than many competing sourcing destinations can offer.
🎯
Why it matters: A product manufactured in Vietnam frequently reaches the EU, the UK, Japan, and other CPTPP or EVFTA markets at a lower landed cost than the same product manufactured somewhere with a thinner trade agreement network. That is a durable structural advantage, not a temporary discount.
2
Deliberate, Sustained Government Support for Manufacturing FDI
Tax breaks, land incentives, new free trade zones
Policy Driven
Vietnam’s government has built manufacturing FDI attraction into national policy for over a decade, with a target for processing and manufacturing to reach roughly 28 to 30 percent of GDP by 2030. Concrete tools back that target: preferential corporate income tax rates for encouraged sectors and locations, land rental exemptions running from 3 to 15 years depending on project type, import duty exemptions on manufacturing machinery and equipment, and a new wave of free trade zones planned for Da Nang, Haiphong, and Ho Chi Minh City through 2030.
🎯
Why it matters: Policy consistency reduces the single biggest risk in any offshore manufacturing decision, the risk that incentives disappear midway through a multi-year investment.
3
Deep, Diversified Manufacturing Base Beyond Assembly
Electronics, textiles, footwear, furniture, and growing automotive components
Sector Depth
Vietnam’s manufacturing FDI is concentrated in globally integrated industries, electronics, machinery, textiles, footwear, and food processing, but investment is gradually shifting toward higher value-added, technology-intensive segments. This is not a single-sector economy dependent on one industry’s fortunes; it spans consumer electronics assembly, garment and footwear production at real scale, and an expanding base in automotive components and renewable energy equipment.
🎯
Why it matters: Sector diversity gives global buyers options within a single country, and reduces the risk that a downturn in one industry undermines the whole manufacturing ecosystem a company depends on.
4
A Credible Home for “China Plus One” Strategies
Geography, trade routes, and geopolitical positioning
Diversification
Vietnam sits directly on major Asian trade routes, shares a border with China, which shortens component logistics for companies shifting final assembly out of China while keeping upstream sourcing nearby, and has absorbed a meaningful share of the manufacturing relocation driven by rising trade tensions and tariff uncertainty between the US and China. For companies pursuing supply chain diversification rather than full relocation, Vietnam offers a workable middle path.
🎯
Why it matters: Reducing single-country concentration risk is now a board-level priority for most global manufacturers, and Vietnam is one of the few destinations with both the trade infrastructure and the industrial base to absorb that volume credibly.
Section 3
Which Sectors Are Driving Vietnam’s Growth
Vietnam’s manufacturing strength is not evenly distributed. Some sectors have scaled to genuinely global size, while others remain smaller but are growing quickly as investment shifts toward higher-value production. Understanding sector-level detail matters more than the country-level narrative when evaluating a specific international sourcing decision.
Sector
Approx. Sector Value
Global Position
Trend
Textiles & Garments
~US$44 billion
Top-tier global exporter
↑ Steady growth
Footwear
~US$20.8 billion
Among world’s largest producers
↑ Steady growth
Electronics & Smartphones
~US$5 billion+ and rising
Major assembly hub for global brands
↑ Fastest-growing FDI segment
Furniture
~US$1.4 billion
Established regional exporter
→ Stable
Automotive Components
Emerging
Growing supplier base
↑ Early but expanding
Renewable Energy Equipment
Emerging
New investment focus
↑ Government-prioritised
The direction of travel matters as much as the current size. Vietnam’s Ministry of Industry and Trade has explicitly prioritised high-tech industries, green and low-carbon manufacturing, and a shift away from low value-added assembly toward more sophisticated production stages, backed by new technical centres such as the one at Hoa Lac Hi-Tech Park. Companies sourcing from Vietnam today are increasingly likely to be dealing with suppliers investing in their own capability, not just their capacity.
Section 4
The Challenges Vietnam Still Has to Solve
None of this means Vietnam is a frictionless choice. Several structural issues are well documented and worth weighing honestly before committing to a Vietnamese manufacturing partnership.
Labour productivity still lags regional peers. Vietnam has historically ranked well behind several Asian competitors on labour productivity, even as wages have risen, meaning the pure low-cost advantage that first attracted investors has narrowed over time.
Import dependency in key export categories. Vietnam remains, in large part, an import-dependent exporter: many of its highest-profile export categories, phones, computers, electronics peripherals, rely heavily on imported components, which limits the share of value actually captured domestically and adds a layer of upstream supply chain risk worth mapping through proper market research for manufacturers before committing.
Energy security in industrial zones. Power reliability concerns, including past blackouts affecting multinational manufacturing hubs in northern industrial parks, remain a live risk factor for energy-intensive production.
Skilled labour shortages in higher-value roles. Investors continue to flag a shortage of skilled workers for R&D and technical activities, which constrains how quickly Vietnam can move into more sophisticated manufacturing segments.
Evolving trade compliance scrutiny. As Vietnam has absorbed manufacturing relocated away from China, it has come under increased scrutiny over rules of origin and transshipment risk from trading partners, making global trade compliance and clean documentation more important than ever for exporters and their buyers alike.
📌 The honest read
Vietnam’s competitive position is not likely to erode overnight, but the country is at an inflection point: it needs to shift from being positioned as cost-effective to being positioned as productive. Companies building a long-term manufacturing relationship in Vietnam should factor this transition into their planning rather than assuming today’s cost and capability profile stays static for the life of the partnership.
Section 5
Vietnam vs. Other “China Plus One” Destinations
Vietnam is not the only beneficiary of manufacturing diversification. India, in particular, is frequently discussed alongside Vietnam as a complementary rather than competing option, since the two countries tend to play to different strengths.
Export-oriented assembly and light manufacturing at speed
Complex, high-tech, and domestic-market-linked manufacturing at scale
Many global manufacturers are not choosing between Vietnam and India, or Vietnam and other Southeast Asian destinations such as Cambodia, Myanmar, and Bangladesh, so much as building a multi-country sourcing footprint that uses each for what it does best. That approach reduces concentration risk further than committing entirely to one alternative destination, but it also means a company will likely need to evaluate and formalise more than one manufacturing partnership at once, using consistent partnership evaluation criteria across markets.
Section 6
Vetting and Formalising a Vietnamese Manufacturing Partnership
Country-level momentum does not de-risk an individual supplier relationship. A promising national trend still leaves a company needing to answer very specific questions about a specific factory: is it legally registered, does it have the production capacity it claims, what happens if a shipment is delayed by a force majeure event, and who owns the specifications once they are shared. This is where most sourcing decisions actually succeed or fail, and it is a different discipline from reading country reports.
🏛️
Confirm legal registration and business status
Verify the company’s registration, incorporation date, and current standing before any commercial discussion goes further.
Government-sourced verification
📄
Protect specifications and pricing before you share them
Put a formal NDA in place, and follow it with a proper business partnership contract, before sensitive product or pricing data changes hands.
NDA-first engagement
📜
Check certifications relevant to your export markets
Review how the agreement handles disruption, including force majeure in global trade, before signing, not after a shipment is delayed.
Contract terms review
🔬
Research the specific province, not just the country
Conditions, incentives, and labour availability vary significantly by province; a tailored market study for manufacturers can uncover this before capital is committed.
🤝 For Verified Long-Term Manufacturing Partnerships
GTsetu: Verified Discovery and Secure Engagement for Manufacturers, Distributors, and Raw Material Suppliers
Vietnam’s growth numbers explain why the country is worth serious consideration. They do not tell you whether a specific manufacturer is who they claim to be, or whether your product specifications will stay confidential during early-stage discussions. That gap is what GTsetu is built to close. It is a structured partnership platform, not a directory or a general marketplace, where every company is verified on 6 government-sourced points before engagement, where discovery is anonymous until mutual interest is confirmed, where NDAs are executed digitally before any commercial information changes hands, and where document exchange happens through an encrypted workspace rather than email attachments.
GTsetu is used by industrial manufacturers, distributors, and raw material suppliers across 100+ countries, including Vietnam, to build out a distributor network, source international wholesale distribution partners, or find manufacturing and technology partnership relationships they intend to keep for years, not a single order cycle. It complements, rather than replaces, on-the-ground factory audits and country-level research, but it removes much of the identity and documentation risk before that deeper diligence even begins.
🏛️
6-Point Government-Sourced Verification
Name, Address, Registration Number, Company Status, Company Type, and Date of Incorporation, verified using government tie-ups before any engagement.
🕵️
Anonymous Discovery
Browse verified manufacturer and distributor profiles across 100+ countries without revealing your own identity or sourcing strategy until you choose to engage.
📄
Built-In NDA Workflow
Digital NDA with timestamped signatures before any pricing, formulations, or product specs are shared. No sensitive information exposed without protection.
🔐
Encrypted Document Workspace
All commercial documents shared through encrypted channels with a full access audit trail, not email attachments.
🌍
100+ Countries, Including Vietnam
Verified manufacturers and distributors across Asia, the Middle East, Europe, Africa, Australia, and the Americas. Built for cross-border partnership formation, not one-off quotes.
🚫
Zero Commission
No success fee, no broker commission, ever. Your partnership economics remain entirely between you and your partner.
It is also worth noting that Vietnam is far from the only region rewriting global sourcing maps. Manufacturers evaluating diversification often run parallel conversations across multiple regions at once, including emerging clusters like the Nigerian industrial and agro cluster, alongside established options in South and Southeast Asia. A platform built for B2B matchmaking across countries, rather than one built around a single geography, makes it easier to run that comparison with consistent verification standards throughout.
FAQ
Frequently Asked Questions
QWhy are global companies choosing Vietnam as a manufacturing partner?
Vietnam combines a fast-growing, FDI-heavy manufacturing base, an expanding network of free trade agreements, competitive and improving labour productivity, and strong sector depth in electronics, textiles, footwear, and furniture. Companies looking to diversify away from single-country sourcing, particularly a China-plus-one strategy, have made Vietnam one of the most preferred relocation destinations in Asia, and 2026’s investment data shows existing investors deepening their commitment rather than just testing the market.
QIs Vietnam still a low-cost manufacturing destination?
Vietnam remains cost-competitive relative to developed markets, but rising wages, workforce constraints, and increasing investor expectations mean the country’s advantage is shifting from pure low cost to productivity and higher value-added output. Vietnam’s government has set explicit targets to move manufacturing further up the value chain rather than compete purely on labour cost, aiming for manufacturing to reach 28 to 30 percent of GDP by 2030 with a substantial high-tech component.
QWhat are the main risks of manufacturing in Vietnam?
Common risks include labour productivity that still lags some regional peers, a heavy reliance on imported inputs for key export categories like electronics, energy security concerns in northern industrial areas, a shortage of skilled talent for R&D and technical roles, and evolving trade compliance requirements including scrutiny of transshipment and rules of origin. Verifying a manufacturing partner’s registration, capacity, and compliance record before committing is essential, and building contingency terms for disruption into the contract from the outset matters just as much.
QHow should a company vet a manufacturing partner in Vietnam?
Beyond a standard factory audit, companies should verify legal registration and business status, confirm actual production capacity against claimed capacity, check compliance history and applicable certifications, and put a formal agreement and confidentiality protections in place before sharing sensitive specifications or pricing. Platforms built for verified B2B partnership formation, rather than general directories or RFQ marketplaces, can substantially reduce this due diligence burden by handling identity verification and document security upfront.
QShould a company choose Vietnam or India for manufacturing diversification?
It depends on the product and priority. Vietnam tends to suit export-oriented assembly and light manufacturing where speed to major Western markets via free trade agreements matters most. India tends to suit more complex, higher-tech manufacturing and production tied to a large domestic market. Many global manufacturers are not choosing one over the other; they are building sourcing footprints that use both, alongside other emerging regions, for what each does best.
Considering Vietnam for Your Next Manufacturing Partnership?
GTsetu is purpose-built for manufacturers, distributors, and raw material suppliers in industrial sectors seeking verified long-term trade partnerships, across 100+ countries including Vietnam, with government-sourced partner verification, built-in NDA workflows, and zero commission.
They represents the product, and research team behind GTsetu, a global B2B collaboration platform built to help companies explore cross-border partnerships with clarity and trust. The team focuses on simplifying early-stage international business discovery by combining structured company profiles, verification-led access, and controlled collaboration workflows.
With a strong emphasis on trust, and disciplined engagement, Team GTsetu shares insights on global trade, partnerships, and cross-border collaboration, helping businesses make informed decisions before entering deeper commercial discussions.