What Is Supplier Concentration Risk and How Can Companies Manage It?
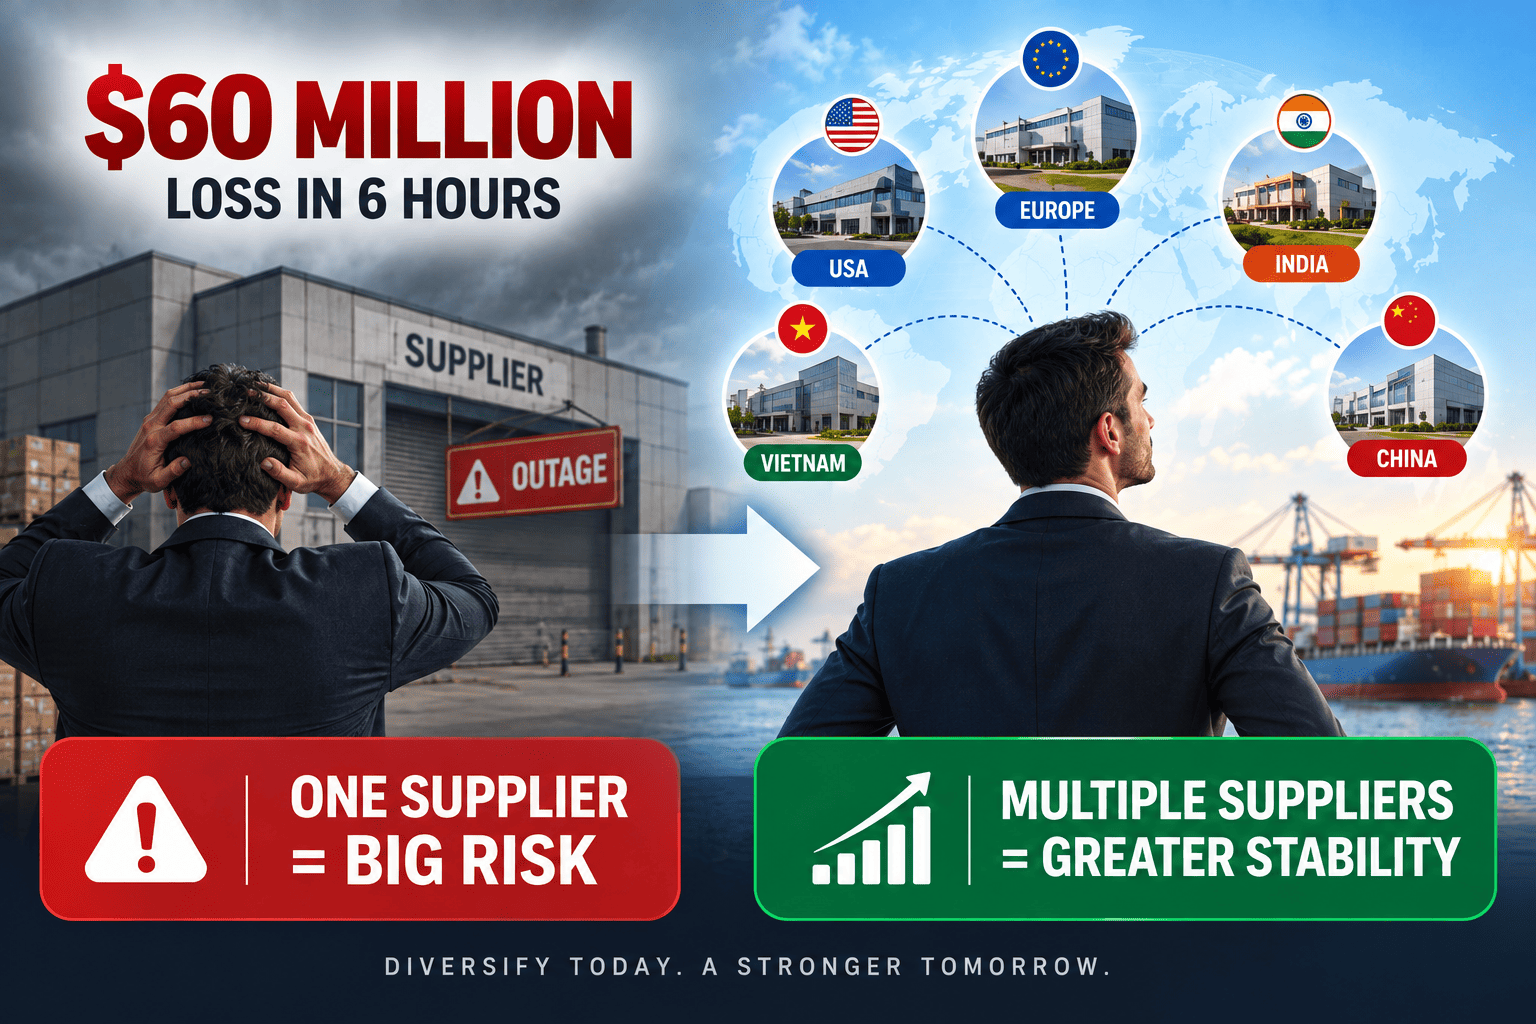
A single vendor outage once cost a major tech company an estimated $60 million in six hours. That is the sharpest illustration of a problem that shows up quietly, gradually, and far more often in manufacturing and sourcing: supplier concentration risk, the exposure a company creates when it depends too heavily on one supplier, one region, or one shared dependency for something critical. It is effectively the outsourcing equivalent of putting all your eggs in one basket, and research suggests most organisations cannot even see the risk clearly, let alone manage it, with 70% of organisations unable to identify their own vendor concentration risks. This article breaks down what supplier concentration risk actually looks like, how to measure it, the hidden dependencies most companies miss, and the practical steps that reduce exposure without sacrificing scale, as part of the broader work of managing cross-border business partnerships.
📅 Published September 9, 2026⏱ 13 min read✍️ GTsetu Editorial🔄 Updated September 9, 2026
It rarely looks dramatic while it is building. A company finds one supplier who delivers reliably, prices well, and understands the specification, so more of the volume moves there. A few years later, that one relationship accounts for the majority of a critical category, and nobody made an explicit decision to get there. Then the supplier has a fire, a labour dispute, a regulatory problem, or simply raises prices at renewal knowing there is nowhere else to go, and the company discovers how much of its business was resting on that single point. Supplier concentration risk is what that slow drift looks like once it becomes visible, and it deserves the same deliberate attention companies already give to global expansion decisions.
Section 1
Supplier Concentration Risk, in Numbers
The scale of the blind spot is easier to see in the data than in any single anecdote. Concentration risk is common, poorly measured, and, in most organisations, simply invisible until something goes wrong.
70%
Of organisations cannot identify their own vendor concentration risks, per Risk Ledger’s research
26.8%
Of security leaders have full visibility into all tiers of their extended supply chains
25%
Commonly cited spend threshold above which a single supplier is flagged as a concentration red flag
$60M
Estimated revenue lost by one company during a single six-hour outage tied to a concentrated dependency
Behind these numbers is a pattern worth sitting with: concentration risk is not primarily a problem of bad suppliers. Even a fully reliable, well-run, financially sound supplier still creates concentration risk if too much depends on it. The 2021 Meta outage, caused by a routine configuration change rather than any malicious act or supplier failure, still cascaded across dozens of dependent internal and external services. The risk lives in the dependency structure itself, not in any single supplier’s competence.
💡 Why this distinction matters
A supplier can pass every quality audit, hold every certification, and still represent a serious concentration risk simply because too much depends on it with no tested alternative. Conversely, a supplier with real weaknesses might create less systemic risk if a company can switch away from it in days rather than months. Concentration risk is about dependency structure, not supplier quality, which is why it needs its own separate assessment.
Section 2
What Supplier Concentration Risk Actually Looks Like
Four Common Patterns
Concentration risk shows up in a handful of recurring patterns, and most companies carry more than one of these at the same time without realising it.
1
Direct Supplier Concentration
One supplier accounts for a large share of a critical category or spend
Single SourceSpend Risk
The most visible form: one vendor supports the majority of a critical input, service, or system. If that supplier suffers a breach, an outage, a labour stoppage, or a financial collapse, the services or products depending on it go down with it. This is also where pricing leverage disappears; high-concentration suppliers can raise prices sharply at renewal knowing the switching cost for the buyer is prohibitive.
🎯
Why it matters: Many companies discovered this pattern the hard way in 2022, when a major videoconferencing vendor raised prices 15-20% across the board, betting correctly that customers who had deeply integrated the platform would absorb the increase rather than migrate.
2
Geographic and Jurisdictional Concentration
Critical suppliers, materials, or production sit in the same region
Regional Risk
When critical operations, raw materials, or production capacity sit within the same country or industrial zone, a single regulatory change, natural disaster, energy grid failure, or political disruption can affect every supplier in that area simultaneously. The 2025 Iberian energy blackout knocked services offline for 12 hours across an entire region regardless of how many separate suppliers a company thought it was using there.
🎯
Why it matters: A company can believe it has diversified by using five different suppliers, only to find all five sit in the same earthquake zone, the same free trade zone, or the same national power grid.
3
Hidden Fourth-Party Concentration
Several “independent” suppliers all rely on the same underlying provider
Shared Dependency
This is the hardest form to see and the most common blind spot: several suppliers that look independent on paper all depend on the same subcontractor, raw material source, logistics provider, or cloud platform underneath. If ten suppliers rely on the same shared input, all ten fail together the moment that input is disrupted, even though a supplier list would show ten separate, seemingly diversified relationships.
🎯
Why it matters: A primary and a backup supplier that quietly rely on the same fourth-party dependency still create a single point of failure; this single check is one of the most common causes of a disaster-recovery plan failing exactly when it is needed most.
4
Roadmap and Operational Concentration
One vendor’s priorities quietly shape a company’s own capability
Strategic Drift
A concentrated supplier’s own product or capacity roadmap naturally follows its broadest customer base, not any individual buyer’s specific needs. When a company depends heavily on one supplier, it loses the ability to shape that supplier’s priorities, and can be left scrambling when the supplier discontinues a service, shifts capacity elsewhere, or changes a specification the buyer had come to depend on.
🎯
Why it matters: Lack of a genuine alternative reduces a company’s negotiating position on everything, not just price, including delivery priority, custom specifications, and how quickly issues get resolved.
Section 3
How to Measure and Assess Your Exposure
No single metric captures the full picture. Measuring concentration risk properly means combining spend data with business-criticality and recovery context, since a small, cheap supplier that nobody tracks closely can still represent a serious hidden exposure. This kind of structured evaluation belongs alongside the partnership evaluation criteria a company already applies to new suppliers.
Metric
What It Measures
Red Flag Threshold
What It Misses on Its Own
Spend Concentration
Share of category spend with top suppliers
Single supplier >20-25% of category spend
Hidden shared dependencies
Criticality Concentration
Whether core business functions rely on one supplier
Single supplier for a mission-critical function
Substitutability and switching time
Substitutability
Number of genuinely independent alternatives available
Zero or one tested alternative
Speed of actually switching
Recovery Time
How long it would take to restore operations if the supplier failed
Unclear or lengthy recovery plan
Whether the backup shares the same risk
Shared-Dependency Mapping
Whether multiple suppliers rely on the same fourth party
Several critical suppliers sharing one hidden provider
Closest to the real risk
The most serious concentration risks are the ones that combine several of these factors at once: high business criticality, broad dependency across multiple functions, few genuine alternatives, and a long recovery time. A useful starting exercise is a heatmap that scores each major supplier or category against these dimensions, which quickly surfaces where diversification effort will actually reduce risk versus where it would just add cost, echoing the kind of upfront market research for manufacturers that should happen before a sourcing decision, not after a disruption.
Section 4
The Hidden Concentration Risk Most Companies Miss
Traditional supplier lists treat each vendor as an isolated entry: assessed, scored, filed, and reviewed on its own timeline. But real supply chains are networks, not lists, and several patterns consistently hide the deepest concentration risk from view.
Direct suppliers sharing the same fourth party. Multiple, seemingly separate suppliers often rely on the same subcontractor, raw material source, or logistics provider without the buyer ever asking the question directly.
Low-spend suppliers creating outsized exposure. Many companies do not centrally track or scrutinise low-value suppliers, yet a cheap, easily approved input used by a large share of the supplier base can create more operational exposure than an obviously large, closely monitored supplier.
Parent companies and acquisitions masking true concentration. Different names, different regions, different product lines can all sit under the same parent company, so what looks like five suppliers on paper may functionally be one, especially after a merger or acquisition compounds the exposure further.
Stale, point-in-time assessments. Annual supplier reviews leave a company blind to new sub-processor relationships, new regional exposure, or ownership changes for the rest of the year, since concentration risk changes continuously, not on a fixed audit cycle.
Contextual data scattered across departments. Procurement, supply chain, and compliance teams often maintain separate supplier records that use different naming conventions for the same underlying company, making it difficult to even ask “do we share a dependency here” without significant manual reconciliation.
📌 The honest read
The goal is not zero concentration; that is neither realistic nor economically sensible in a global supply chain. Modern manufacturing and sourcing inevitably shares some regions, some raw material sources, and some logistics providers across an entire industry. The real objective is making sure any concentration that exists is known, deliberate, and survivable, rather than invisible until an incident forces it into view.
Section 5
Diversification vs. Scale: Finding the Right Balance
Diversification is not automatically the right answer for every category, and over-correcting has its own costs. Understanding where the trade-off actually sits helps avoid both overconcentration and its opposite, wasteful over-diversification.
Approach
What It Optimises For
Main Risk If Overdone
Best Fit
Concentration with a Strategic Partner
Scale economics, deep collaboration, volume discounts
Single point of failure, loss of leverage at renewal
Non-critical, easily replaced categories
Diversification Across 2+ Suppliers
Resilience, competitive pricing pressure
Lost volume discounts, more relationships to manage
Mission-critical or hard-to-substitute categories
Sprawling, Granular Diversification
Maximum theoretical redundancy
Lost scale economics, disjointed operations
Rarely the right default; usually overcorrection
The practical target most frameworks converge on is a tight core of well-governed strategic partners for the categories where deep collaboration adds real value, paired with a bench of genuinely tested alternatives for anything mission-critical or hard to substitute. That balance depends on knowing which categories are actually critical, which is where formal international sourcing of manufacturing materials discipline pays off long before a concentration crisis forces the question.
Section 6
Practical Steps to Reduce Concentration Risk
Once a company has identified where its concentration risk actually sits, a handful of concrete actions reduce exposure without requiring a wholesale rebuild of the supply chain overnight.
📊
Set explicit concentration thresholds
Define the maximum share of spend or supply any single vendor can represent in a critical category, and flag any outlier for review.
Policy-driven monitoring
🔀
Maintain a genuinely independent backup
For mission-critical categories, keep at least one tested alternative, and confirm it does not share the same hidden fourth-party dependency as the primary supplier.
Evaluate alternatives for major spend categories every 1-2 years, even without an active intention to replace the incumbent, to keep the competitive landscape current.
Scheduled review
🤝
Get expert support for a first diversification move
🤝 For Verified, Diversified Supplier Relationships
GTsetu: Verified Discovery and Secure Engagement for Manufacturers, Distributors, and Raw Material Suppliers
Reducing supplier concentration risk starts with actually being able to find and vet genuine alternatives, not just adding another name to a spreadsheet that turns out to share the same hidden dependency as everything else on the list. That gap is what GTsetu is built to close. It is a structured partnership platform, not a directory or a general marketplace, where every company is verified on 6 government-sourced points before engagement, where discovery is anonymous until mutual interest is confirmed, where NDAs are executed digitally before any commercial information changes hands, and where document exchange happens through an encrypted workspace rather than email attachments.
GTsetu is used by industrial manufacturers, distributors, and raw material suppliers across 100+ countries to build genuinely independent supplier relationships, expand a distributor network, or find a reliable supply chain partner in a new region rather than deepening exposure to an existing one. It complements, rather than replaces, on-the-ground audits and dependency mapping, but it removes much of the identity and documentation risk before that deeper diligence even begins, addressing the same trust gap explored in why trust breaks in global deals.
🏛️
6-Point Government-Sourced Verification
Name, Address, Registration Number, Company Status, Company Type, and Date of Incorporation, verified using government tie-ups before any engagement.
🕵️
Anonymous Discovery
Browse verified manufacturer and distributor profiles across 100+ countries without revealing your own identity or sourcing strategy until you choose to engage.
📄
Built-In NDA Workflow
Digital NDA with timestamped signatures before any pricing, formulations, or product specs are shared. No sensitive information exposed without protection.
🔐
Encrypted Document Workspace
All commercial documents shared through encrypted channels with a full access audit trail, not email attachments.
🌍
100+ Countries of Verified Alternatives
Verified manufacturers and distributors across Asia, the Middle East, Europe, Africa, Australia, and the Americas. Built for cross-border partnership formation, not one-off quotes.
🚫
Zero Commission
No success fee, no broker commission, ever. Your partnership economics remain entirely between you and your partner.
Diversification efforts also work best when treated as an ongoing discipline rather than a one-time project. Companies actively reducing concentration risk are increasingly using B2B matchmaking tools to surface qualified alternatives across regions, drawing on the same standards applied to cross-border manufacturing partnerships in global supply chains, and building relationships with international wholesale distributors in more than one region so a single disruption never threatens the entire distribution channel at once.
FAQ
Frequently Asked Questions
QWhat is supplier concentration risk?
Supplier concentration risk is the exposure a company creates when it depends too heavily on a small number of suppliers, a single region, or one underlying provider for a critical input. It represents a single point of failure: if that supplier, region, or shared dependency is disrupted, the company’s ability to operate is disrupted along with it.
QWhat is a safe level of supplier concentration?
There is no universal safe threshold. A common rule of thumb flags any single supplier above 20-25% of total spend or supply for a critical category as a risk worth reviewing, but business criticality, substitutability, and recovery time matter more than the percentage alone. A concentration becomes significant when it affects a critical service, offers few genuine alternatives, or would take a long time to recover from.
QHow is supplier concentration risk different from ordinary supplier risk?
Ordinary supplier risk asks whether a specific supplier could cause harm, through poor quality, weak financials, or compliance failures. Supplier concentration risk asks how much of the business would be affected if that dependency failed, including hidden cases where several seemingly independent suppliers all rely on the same fourth-party subcontractor, raw material source, or region.
QHow can a company reduce supplier concentration risk without losing scale benefits?
Most companies do not need to eliminate concentration entirely; over-diversifying a routine category can cost more in lost volume discounts than it saves in risk reduction. The practical approach is to set concentration thresholds for critical categories, maintain at least one genuinely independent backup supplier for anything mission-critical, verify that backup and primary suppliers do not share the same hidden dependency, and re-compete major categories periodically to keep alternatives current.
QHow often should supplier concentration risk be reassessed?
A full portfolio review at least annually is a reasonable baseline, with lighter refresh assessments quarterly. Reassessment should also be triggered by major shifts, such as a supplier acquisition, a new subcontractor relationship, a significant change in spend allocation, or a disruption event anywhere in the supply chain that reveals a previously unknown shared dependency.
Looking to Diversify Away from a Concentrated Supplier?
GTsetu is purpose-built for manufacturers, distributors, and raw material suppliers in industrial sectors seeking verified long-term trade partnerships, across 100+ countries, with government-sourced partner verification, built-in NDA workflows, and zero commission.
They represents the product, and research team behind GTsetu, a global B2B collaboration platform built to help companies explore cross-border partnerships with clarity and trust. The team focuses on simplifying early-stage international business discovery by combining structured company profiles, verification-led access, and controlled collaboration workflows.
With a strong emphasis on trust, and disciplined engagement, Team GTsetu shares insights on global trade, partnerships, and cross-border collaboration, helping businesses make informed decisions before entering deeper commercial discussions.